Adobe expects shoppers to put $807 million of Black Friday spending on buy now, pay later this year, and $21.3 billion over November and December. Most of it will be Pay-in-4: a quarter at checkout, the rest every two weeks, no interest. On the checkout page that looks like a quarter of the price.
It is not free money and it is not a trap. It is a schedule. Four plans opened over one weekend become four payments that land on the same paychecks for six weeks, on top of rent and every other bill. This guide follows one household through Black Friday weekend with Klarna, Afterpay, Affirm and PayPal, using each provider's published terms, and shows which paycheck comes up short, what a missed payment costs, and how much Pay-in-4 a paycheck can actually carry.
It is written for US shoppers. If you sell during Black Friday, our discount break-even guide covers the store's side. Longer monthly BNPL loans with interest are covered briefly below; store credit cards are not.
The forecast$807 million on one Friday
Source: CalculatorAI · calculatorai.app · Adobe Digital Insights, September 28, 2026; Federal Reserve, Economic Well-Being of U.S. Households in 2025 (May 2026)
The Fed's numbers are the ones to read twice. A quarter of BNPL users paid late at least once last year, and 64% of those were charged extra for it. Because most plans pull payments automatically from a checking account, 11% of users had a BNPL payment set off an overdraft or non-sufficient-funds fee at their bank, a cost that never appears on the BNPL app.
The pattern also clusters at the holidays. The Consumer Financial Protection Bureau found that about 63% of BNPL borrowers had more than one loan open at the same time at some point in the year, and 33% borrowed from more than one provider. That is the scenario the rest of this guide models.
The termsFour Pay-in-4 plans, four sets of rules
All four big providers offer the same basic product: four equal payments, two weeks apart, 0% interest when paid on time. They differ on what happens when a payment fails.
PayPal Pay in 4
- Interest on Pay-in-4
- 0%
- Late fee
- $0
- Fee cap or note
- Purchases of $10 to $2,000; not available in Missouri
Affirm
- Interest on Pay-in-4
- 0% on Pay in 4
- Late fee
- $0
- Fee cap or note
- Monthly plans run 0% to 36% APR
Klarna
- Interest on Pay-in-4
- 0% when paid on time
- Late fee
- Up to $7
- Fee cap or note
- Charged if a second collection attempt fails; all fees together never exceed 25% of the order
Afterpay
- Interest on Pay-in-4
- 0% on most plans
- Late fee
- Up to $8 per missed payment
- Fee cap or note
- All fees together never exceed 25% of the order; some plans carry a finance fee
| Provider | Interest on Pay-in-4 | Late fee | Fee cap or note |
|---|---|---|---|
| PayPal Pay in 4 | 0% | $0 | Purchases of $10 to $2,000; not available in Missouri |
| Affirm | 0% on Pay in 4 | $0 | Monthly plans run 0% to 36% APR |
| Klarna | 0% when paid on time | Up to $7 | Charged if a second collection attempt fails; all fees together never exceed 25% of the order |
| Afterpay | 0% on most plans | Up to $8 per missed payment | All fees together never exceed 25% of the order; some plans carry a finance fee |
Source: CalculatorAI · calculatorai.app · klarna.com, afterpay.com, paypal.com, Affirm Form 10-K (fiscal 2025) and investors.affirm.com
No late fee does not mean no consequence. A provider that charges nothing can still pause your account, refuse the next purchase, and pass an unpaid balance to collections. Your bank can still charge you when an automatic payment overdraws the account.
The weekendFour plans, one $2,200 calendar
Take the household from our bills by paycheck guide: a net paycheck of $2,100 every other Friday and nine monthly bills totalling $2,542. In this calendar Black Friday, November 27, 2026, is also a payday.
Over the long weekend, they make four purchases, each split into four payments:
TV · Klarna
- Price
- $600
- Each payment
- $150
- Payment dates
- Nov 27 · Dec 11 · Dec 25 · Jan 8
Sneakers and a jacket · Afterpay
- Price
- $240
- Each payment
- $60
- Payment dates
- Nov 28 · Dec 12 · Dec 26 · Jan 9
Gifts · Affirm
- Price
- $360
- Each payment
- $90
- Payment dates
- Nov 29 · Dec 13 · Dec 27 · Jan 10
Laptop · PayPal
- Price
- $1,000
- Each payment
- $250
- Payment dates
- Nov 30 · Dec 14 · Dec 28 · Jan 11
| Purchase | Price | Each payment | Payment dates |
|---|---|---|---|
| TV · Klarna | $600 | $150 | Nov 27 · Dec 11 · Dec 25 · Jan 8 |
| Sneakers and a jacket · Afterpay | $240 | $60 | Nov 28 · Dec 12 · Dec 26 · Jan 9 |
| Gifts · Affirm | $360 | $90 | Nov 29 · Dec 13 · Dec 27 · Jan 10 |
| Laptop · PayPal | $1,000 | $250 | Nov 30 · Dec 14 · Dec 28 · Jan 11 |
Source: CalculatorAI · calculatorai.app · Illustrative household; drafts/bnpl-black-friday-numbers.mts
Every payment is small next to its price. Together they add up to $550 every two weeks for six weeks, and because all four plans started within four days of each other, each round lands within the same paycheck.
By paycheckWhere the $550 rounds actually land
On average, the household can afford this. The bills take $2,542 a month, two paychecks bring in $4,200, and $550 per paycheck fits inside the difference. The trouble is that the bills do not fall evenly: rent ($1,450 on the 1st) makes one paycheck in two much heavier than the other. The BNPL rounds land on all of them alike.
Nov 27
- Bills due
- $1,667
- BNPL due
- $550
- Left over
- −$117
Dec 11
- Bills due
- $675
- BNPL due
- $550
- Left over
- $875
Dec 25
- Bills due
- $1,832
- BNPL due
- $550
- Left over
- −$282
Jan 8
- Bills due
- $625
- BNPL due
- $550
- Left over
- $925
| Paycheck | Bills due | BNPL due | Left over |
|---|---|---|---|
| Nov 27 | $1,667 | $550 | −$117 |
| Dec 11 | $675 | $550 | $875 |
| Dec 25 | $1,832 | $550 | −$282 |
| Jan 8 | $625 | $550 | $925 |
Source: CalculatorAI · calculatorai.app · Computed with the Bill Tracker's By paycheck engine; drafts/bnpl-black-friday-numbers.mts
Two of the four paychecks come up short: $117 on Black Friday itself and $282 on Christmas Day, the paycheck that also has to cover January's rent. Without the plans, those same paychecks ended with $433 and $268. The plans did not make the household poorer on paper; they put $550 on the two paychecks that had the least room.
The ceilingHow much Pay-in-4 your paychecks can carry
The household could have had all four purchases with none of the shortfall — if they had kept the total within what their tightest paycheck can absorb. A Pay-in-4 round lands on four consecutive paychecks, so the limit is set by the one with the least left over after bills.
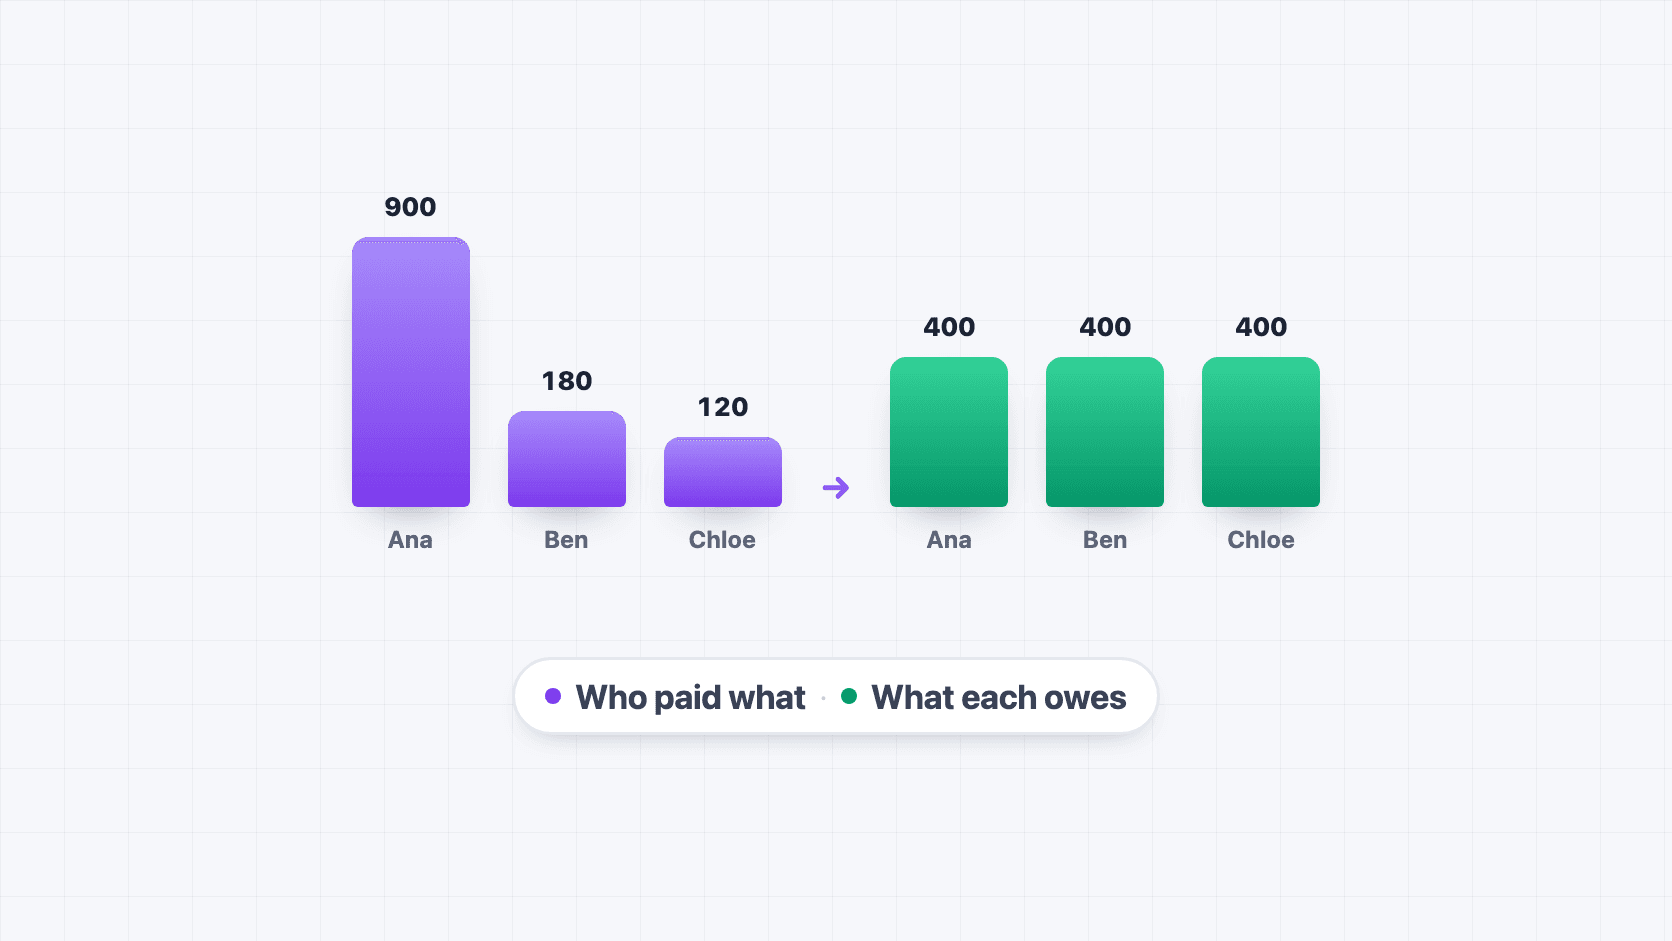
Smallest leftover across the next four paychecks × 4$268 (the Dec 25 paycheck) × 4 = $1,072 of purchases($268 − $100) × 4 = $672So the honest limit for this household is about $1,072 of Pay-in-4 purchases over the weekend, not $2,200, and closer to $670 if they want to keep $100 spare in every paycheck. That number is personal: it depends on your pay, your bills and where your rent falls, which is why it is worth working out before November 27 rather than at checkout.
Late feesWhat a missed payment costs as an APR
A $7 or $8 fee sounds trivial next to a $600 TV. Measured against the payment it was charged on, and the two weeks until the next payment collects it, it is the most expensive credit in this guide.
Missing one $60 Afterpay payment costs the same as borrowing at 348% a year.
Show these figures as a table
| Value (% a year) | |
|---|---|
| Credit card, average APR on accounts paying interest — 22.15% | 22 |
| All four plans miss one round · $15 in fees on $550 — 71% | 71 |
| Klarna · $7 fee on a $150 payment — 122% | 122 |
| Afterpay · $8 fee on a $60 payment — 348% | 348 |
Source: CalculatorAI · calculatorai.app · Provider terms checked October 7, 2026; Federal Reserve G.19 (Q2 2026); drafts/bnpl-black-friday-numbers.mts
Smaller purchases are hit hardest, because the fee is flat. The 25% cap is what protects them: on a $40 order paid as four $10 payments, four missed payments at $8 each would be $32 in fees, and the cap stops them at $10. The Affirm and PayPal plans in the example charge no late fee at all, so the whole missed round costs $15, all of it from the Klarna and Afterpay plans.
The alternativesA card, a monthly plan, or saving first
The fair comparison is not Pay-in-4 against nothing. It is Pay-in-4 against the other ways to buy the same $2,200 of things.
Paying the card at the minimum takes 9 years and 8 months and costs more in interest than the purchases.
Show these figures as a table
| Value ($ of interest) | |
|---|---|
| Saved up first, or Pay-in-4 paid on time — $0 | 0 |
| Card, paid down $550 every two weeks — $28 | 28 |
| Card, paid off in 6 months · $391/mo — $144 | 144 |
| Card, minimum payments only · 116 months — $2,562 | 2,562 |
Source: CalculatorAI · calculatorai.app · Federal Reserve G.19 (Q2 2026); drafts/bnpl-black-friday-numbers.mts
Three things stand out:
- On time, Pay-in-4 beats a credit card. It is 0% against 22.15%, though the gap on a six-week schedule is only $28. If you pay your card statement in full every month, the card's grace period makes it 0% too, with stronger dispute rights on a faulty purchase.
- Monthly BNPL is a loan. Affirm's and PayPal's monthly plans run up to 36% and 35.99% APR. At the top of Affirm's range, the $1,000 laptop over 12 months costs $206 in interest, more than a card paid off in six months.
- Saving first is the cheapest and it is still possible. In this calendar there are four paydays between now and Black Friday: October 16 and 30, November 13 and 27. Setting aside $550 from each pays for all four purchases in cash, the same $550 the plans would have taken, just before the sale instead of after it. Our holiday gift budget guide builds that kind of weekly target for gifts.
Credit scoreWhat BNPL does and does not report
Most people get this wrong in both directions. In the Fed's survey, 53% of BNPL users believed that paying on time helps their credit score. At the time of the survey, it did not: on-time BNPL payments were not counted in scores at any of the three major credit bureaus.
Affirm reports all of its US loans, including Pay in 4, to Experian and TransUnion, but as of its November 2025 statement that data is kept out of the scores lenders see. Other providers report only some products or none. The practical rule:
- Paying on time does not build credit with most Pay-in-4 plans today.
- Missing a payment usually does not show up on its own either, but an unpaid balance sent to a collection agency can, and collections hurt a score for years. What moves your credit score explains how much.
- A card is still where your score is built. If you are trying to build credit, a card paid in full does that and Pay-in-4 mostly does not.
When it is finePay-in-4 done right
Pay-in-4 is a reasonable tool when the purchase was in the budget anyway and you only want to spread the cash flow. The checklist:
It is a 0% plan
The checkout screen says no interest and no finance fee. If it shows an APR, compare it with your card before you accept.
It fits your tightest paycheck
Each payment fits inside the leftover of the heaviest paycheck it lands on, not just the monthly average.
Two plans at most at a time
Stacking is where the shortfalls come from. Finish one round before you start another.
Paid from a funded account
Autopay draws from an account with a cushion, so a payment never overdraws it. Paying installments with a credit card you then carry turns 0% into 22%.
Not for groceries or bills
In the Fed's survey, 45% of people using BNPL for groceries said it was the only way they could afford them. That is a budget problem, not a payment-plan problem.
Returns tracked
A plan usually changes only once the store processes the refund. Keep paying until the app shows the new balance.
Set it upPut every plan next to your bills
The reason the household above came up short is that the plans lived in four different apps and the rent lived in a fifth. The fix is to put them on one calendar with your pay schedule.
Enter your pay schedule
In the free Bill Tracker, set your payday (every 2 weeks, twice a month or monthly) and the net amount of each paycheck.
Add each plan as a bill
Amount = one payment, frequency = every 2 weeks, first due date = the checkout date, last due date = the fourth payment. The plan stops on its own after the last payment.
Add the late fee
Enter the provider's late fee on the bill, so the tracker shows what is at risk if a payment is missed.
Check the By paycheck view
It shows which paycheck covers which bills and plans and what is left after each. A negative number before you buy is the cheapest warning you will get.
Keep reminders on
A reminder a few days before each payment gives you time to move money before autopay runs.
Where these numbers come from
- Forecast: Adobe Digital Insights, US holiday forecast published September 28, 2026: $275.1 billion online for November 1 – December 31, BNPL $21.3 billion (up 6.6%), $807 million on Black Friday and $1.09 billion on Cyber Monday.
- BNPL use: Federal Reserve, Economic Well-Being of U.S. Households in 2025 (May 2026), survey fielded October 2025: 16% used BNPL; 26% of users paid late; 64% of late payers were charged extra; 11% had an overdraft or NSF fee; 53% wrongly believed on-time payments help their score. CFPB research released January 2025 (2022 data from six large BNPL firms): about 63% of borrowers held multiple simultaneous loans, 33% across multiple firms.
- Provider terms: read on each provider's US pages on October 7, 2026 — Klarna Pay in 4 (late fee up to $7, total fees capped at 25% of the order), Afterpay (up to $8 per missed installment, capped at 25%; finance-fee example of $110 at 36% APR), PayPal Pay in 4 and Pay Monthly ($10–$2,000, no late fees; 0–35.99% APR), Affirm's fiscal 2025 Form 10-K (no late fees; bank partners allow rates up to 36%) and its November 2025 statement on credit reporting. Terms change; the checkout screen is the final word.
- Household: $2,100 net every other Friday from October 2, 2026, nine monthly bills totalling $2,542 (rent $1,450 on the 1st), the same household as in bills by paycheck. Four purchases totalling $2,200, with first payments on November 27–30. Paycheck totals were computed with the Bill Tracker's own By paycheck engine; each paycheck covers bills and plan payments due from its payday through the day before the next.
- Late fee as an APR: fee ÷ payment × 365 ÷ 14, assuming the missed payment is collected with the next scheduled one two weeks later. Paying sooner lowers the rate; a second fee raises it.
- Credit card: 22.15% APR, the Federal Reserve G.19 average for accounts assessed interest, Q2 2026. Minimum payment modelled as interest plus 1% of the balance, at least $35; issuers' formulas vary, and a higher minimum shortens the payoff. "Paid down $550 every two weeks" assumes interest is charged from the purchase date (no grace period), which overstates the cost for anyone who pays the statement in full.
FAQFrequently asked questions
Is buy now, pay later a good idea on Black Friday?
It can be, if the plan is 0%, each payment fits the paycheck it lands on, and you would have bought the item anyway. It becomes expensive when several plans stack up and a payment fails.
Does Klarna or Afterpay charge interest?
Not on standard Pay-in-4 plans paid on time. Klarna can charge a late fee of up to $7 and Afterpay up to $8 per missed payment, both capped at 25% of the order. Some Afterpay plans carry a finance fee, shown at checkout.
Does Affirm charge late fees?
No. Affirm says it has never charged late fees. Its Pay in 4 is 0%, while its monthly plans can carry an APR of up to 36%.
Does buy now, pay later affect your credit score?
On-time payments generally do not help your score today. A missed payment usually does not appear on its own, but a balance sent to collections can damage your score.
How many buy now, pay later plans is too many?
More than your tightest paycheck can carry. Multiply the smallest amount left over after bills across your next four paychecks by four: that is roughly the most you can put on Pay-in-4 at once.
Can I pay off a Pay-in-4 plan early?
Yes. Klarna, Afterpay, Affirm and PayPal all let you pay early without a penalty, which is a good use for a lighter paycheck.
Buy it once, pay for it on purpose
Pay-in-4 does not change the price of anything; it changes the date you pay for it. On Black Friday that date lands on paychecks that already have rent, Christmas and January to cover. Check the paychecks before the sale, keep the total under what the tightest one can carry, and put every plan where you can see it.
Add your pay schedule and each plan to the free Bill Tracker to see, paycheck by paycheck, what is left after the holidays.