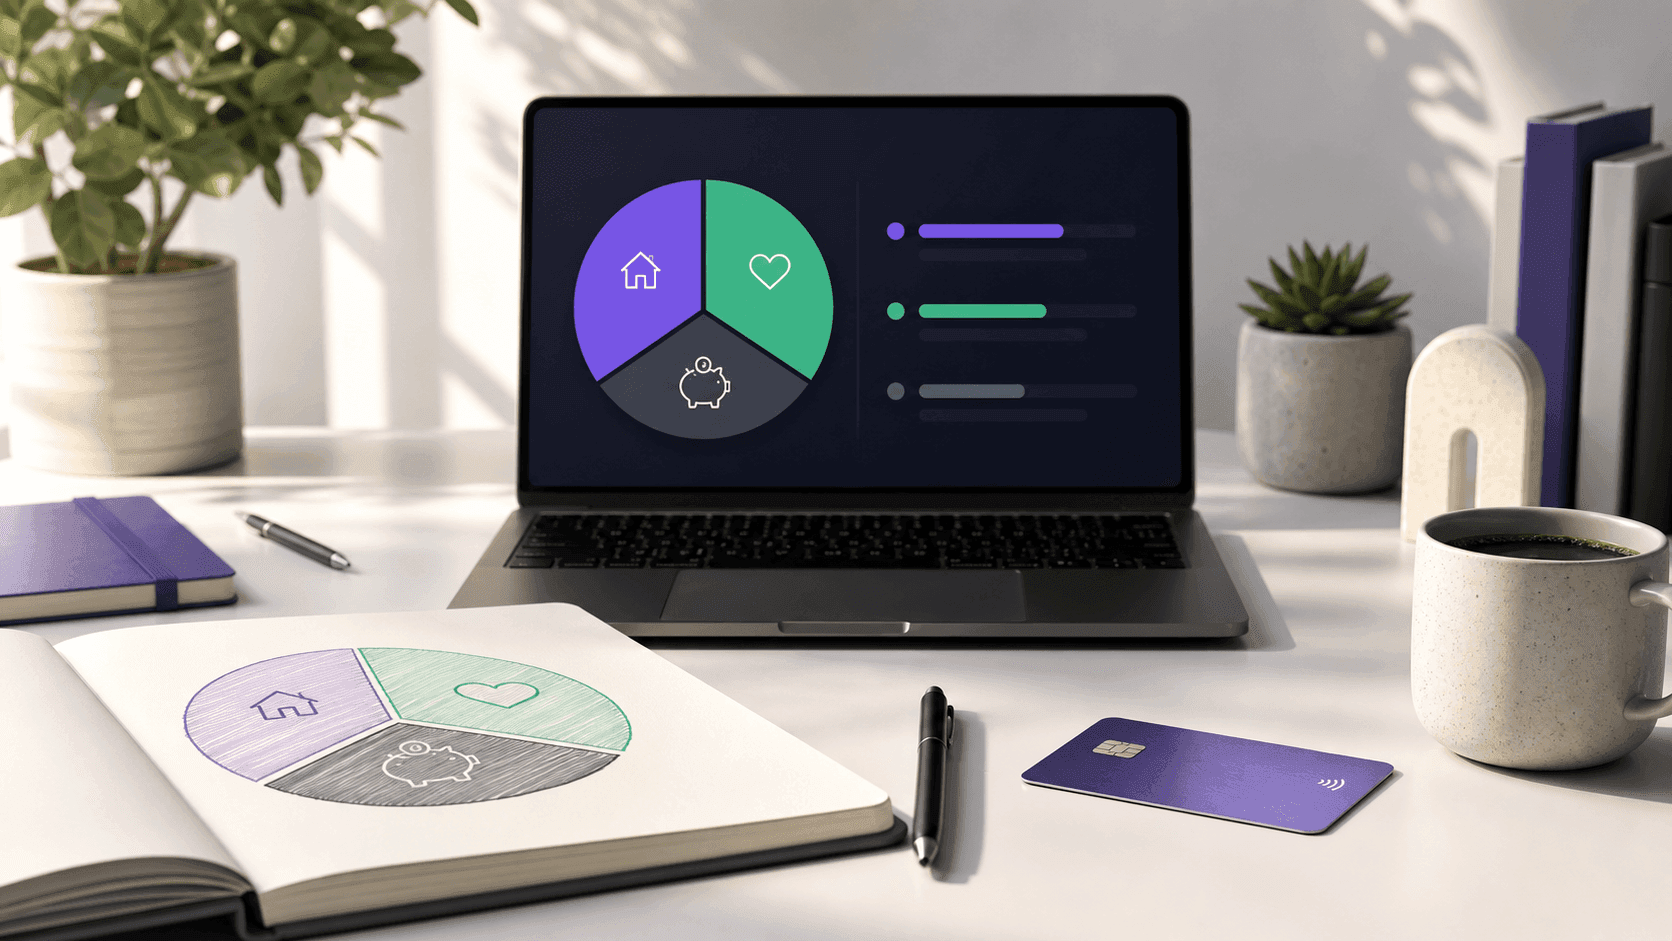
The 50/30/20 rule is the simplest budget that actually works. Instead of tracking forty categories, you split your take-home pay three ways: 50% to needs, 30% to wants, and 20% to savings and debt. It is popular because it is easy to remember and flexible enough to keep.
Here is how it works, a real example, and how to stick to it without spreadsheets.
Three bucketsThe three buckets
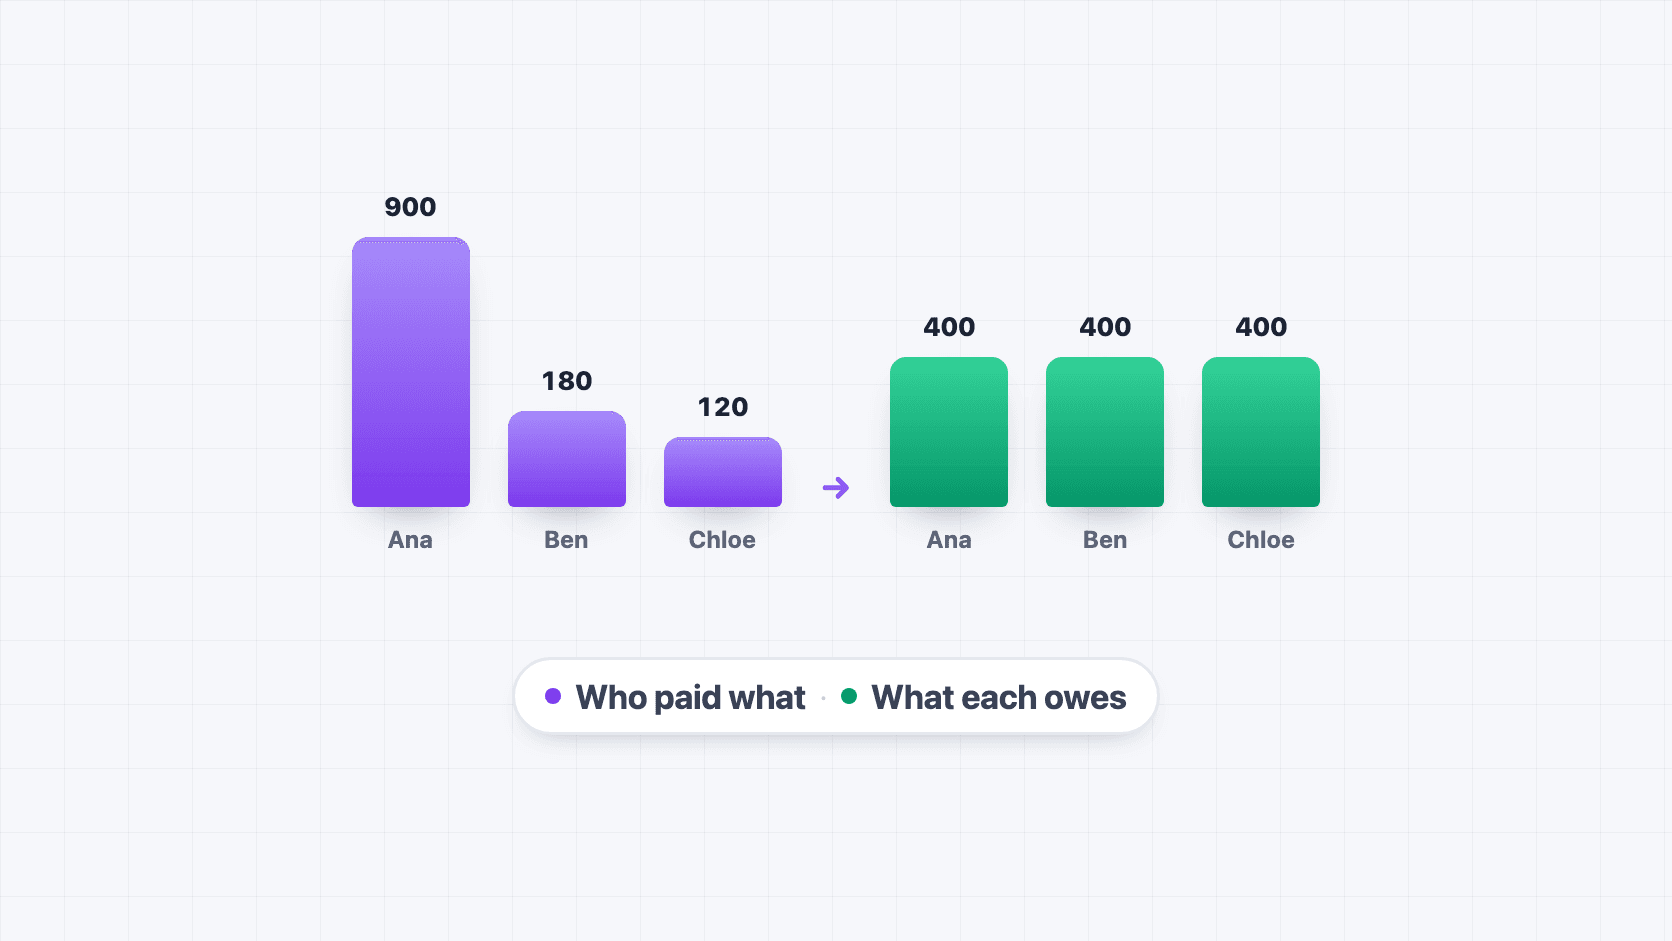
- 50% — Needs. The essentials you cannot skip: rent or mortgage, utilities, groceries, insurance, minimum debt payments, transportation to work. Fuel is the need that moved most in 2026 — at $4.46 a gallon a 30 mpg commute costs $44 a month more than a year earlier (what gas prices cost by vehicle). (Sharing a flat? Split the rent and bills fairly before you size this bucket.)
- 30% — Wants. The lifestyle stuff: dining out, streaming, hobbies, travel, upgrades, anything you enjoy but could live without. Big sales test this bucket hardest; our Prime Big Deal Days guide separates a real saving from a new want. Holiday gifts come out of the same 30%, so plan them by person before December. (A yearly phone upgrade is the classic want dressed as a need — the iPhone 18 Pro, four ways puts a per-day price on it.)
- 20% — Savings & debt payoff. Emergency fund, retirement, investments, and extra payments beyond the minimums on debt. The emergency-fund share belongs in an account that pays: what high-yield savings earns after the Fed hike.
The key detail: it is based on your take-home (after-tax) pay, not your gross salary. The gap between the two widens as income rises: a married couple in Florida earning $100,000 keeps about 85%, while a $55 million NFL salary keeps about 57%.
Worked exampleA worked example
Say your paycheck after taxes is $4,000 a month. (Paid every other week instead? The bills still fall monthly — bills by paycheck shows how to give each one to the right paycheck.) The 50/30/20 split is:
- Needs — $2,000 (50%)
- Wants — $1,200 (30%)
- Savings & debt — $800 (20%)
If your rent, utilities, groceries and insurance add up to more than $2,000, your needs are over 50% — a sign to either trim fixed costs or borrow a little from the "wants" bucket while you fix it. (Housing is the line that breaks it — our salary-to-buy-a-home study shows how far a mortgage payment sits from 50% in six countries.) The Budget Calculator does this math for you: enter your take-home pay and it returns each bucket instantly.
CategorisingHow to categorize honestly
The tricky part is "need vs. want." A few rules of thumb:
- Groceries are a need; restaurants are a want.
- Basic phone plan is a need; the newest phone on a payment plan is a want.
- Minimum debt payment is a need; extra payoff is in the 20% bucket.
- A car to get to work is a need; the upgrade to a nicer one is a want.
Be honest, but do not agonize — the goal is a plan you will actually follow, not perfection.
When it does not fitWhat if the numbers do not fit?
- High cost of living? In expensive cities, needs often run above 50%. Aim to keep it under 60% and protect at least 10% savings while you work on the rest — that is close to how Ramit Sethi’s Conscious Spending Plan is built, with fixed costs allowed up to 60% and investing given its own 10% floor.
- Paying off debt? It is fine to shift toward the 20% (and even borrow from "wants") until high-interest debt is gone.
- Just starting out? Even 50/30/20 with a small income beats no plan. Automate the 20% first so it happens before you can spend it.
Sticking to itHow to actually stick to it
A budget only works if you can see whether you are on track. That is where a tracker beats a mental tally:
- Set a monthly budget per category in the Expenses Tracker.
- Log or import your spending (or snap receipts).
- The dashboard shows spend vs. limit per category, your net cash flow and your savings rate — so you know in real time whether "wants" is creeping over 30%.
Reviewing it once a week for five minutes is enough to keep the whole thing on the rails.
FAQFrequently asked questions
Is 50/30/20 based on gross or net income? Net — your take-home pay after taxes. That is what actually hits your account.
What counts as a "need"? Anything you genuinely cannot skip to live and work: housing, utilities, groceries, insurance, minimum debt payments and basic transport. If you could pause it without real consequence, it is a want.
What if I cannot save 20%? Start with what you can — even 5–10% builds the habit — and automate it. Trim fixed "needs" (the biggest lever) over time to free up the rest.
Does debt payoff count toward the 20%? Minimum payments are a "need"; anything extra toward paying down debt counts in the 20% bucket.
Next stepTry it with your numbers
Get your split in seconds with the Budget Calculator, then set category budgets and track the real thing in the Expenses Tracker.